Miami Beach Condos & Homes for Sale: Buyer's Guide
This guide expands on Javier's Miami buyer representation.
Short answer
Miami Beach condominiums, houses and waterfront homes require different evaluation, and there is no universal winner. Start with property type and intended use, then compare location, the building or the street, condition, ownership costs and the alternatives currently available in the same segment. This page explains how to evaluate the choice. Live listings belong on Javier's Miami property search; current local market interpretation belongs in his Miami Beach market overview; and neighborhood and lifestyle context sits in the Miami Beach community guide.
What property types can a buyer consider in Miami Beach?
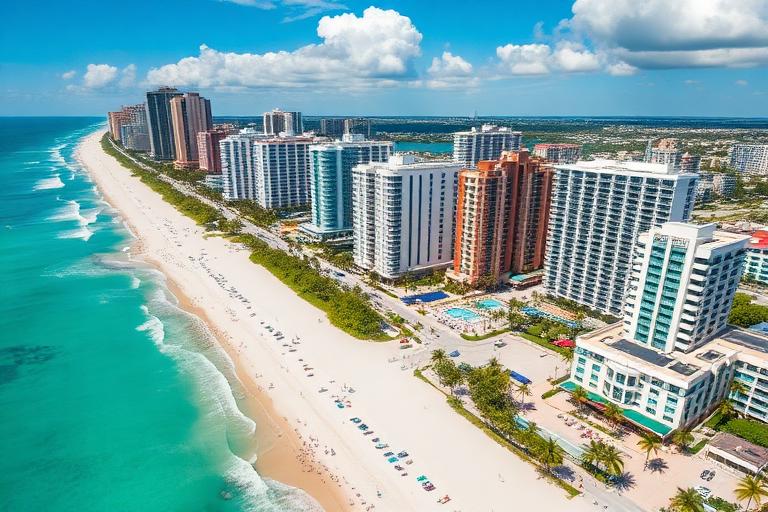
Miami Beach is a barrier island city with a mixed residential stock. For this buyer guide, the three main residential categories are condominiums, single-family houses and waterfront homes, and the differences between them are structural rather than cosmetic. Deciding which category fits your intended use is the first decision, because it determines everything you evaluate afterwards.
Condominiums
A condominium purchase is three things at once: the unit itself, an interest in the building it sits in, and membership in the association that governs and maintains it. That structure is the reason building-level review matters as much as unit-level review, and the reason two similar units in different buildings can be very different purchases.
Single-family homes
A house is the structure plus the land plus the street it sits on. The owner generally carries direct responsibility for the structure and site, and a house may offer more physical separation, private outdoor space and direct control, subject to any association, deed, zoning and permitting restrictions that apply. The location works at the level of the individual block rather than the building. Miami Beach houses are concentrated in specific residential areas rather than spread evenly across the city.
Waterfront homes
A waterfront home is a house with an additional, site-specific layer: the shoreline, any seawall or dock arrangement, the orientation and frontage, and the way the site meets the water. That layer is particular to the property, which is why waterfront homes are compared against other waterfront homes rather than against inland houses.
Townhomes and small multifamily properties also exist in parts of the city. Their ownership structure and responsibilities should be verified property by property; a townhome, for example, can be condominium or fee-simple/association-governed depending on the community. In practice they are evaluated as a variation on one of the three categories above.
Condominiums
What you buy: A unit, plus an interest in a building and membership in an association.
What you evaluate: Unit characteristics, building age and condition, association finances and rules, ownership costs and current competing units.
Who it can suit: Buyers who want shared maintenance, building services and a lock-and-leave arrangement, and who accept shared governance.
Single-family homes
What you buy: A house and the land it sits on, in a specific street and location.
What you evaluate: Structure, systems and condition, lot and outdoor space, orientation and privacy, permit history, and any association or deed restrictions.
Who it can suit: Buyers who want control over the property and more privacy, and who are prepared to carry maintenance directly.
Waterfront homes
What you buy: A house and land, plus a site-specific relationship to the water.
What you evaluate: Everything a house requires, plus shoreline and seawall, dock or lift where present, frontage and orientation, access, and property-specific flood and insurance circumstances.
Who it can suit: Buyers for whom the water itself is part of the use, and who will verify the site rather than assume it.
Condo or house: what actually changes for the buyer
In Miami Beach the practical differences show up in seven places. Ownership structure differs: a condominium unit comes with shared interests and an association, while a buyer of a single-family house generally owns the structure and land directly, subject to any applicable restrictions or association. Maintenance responsibility differs: a building maintains shared elements on a collective budget, whereas a homeowner arranges and pays for work directly. Governance and fees apply where an association exists, which means documents, rules and a recurring cost that a freestanding house without an association does not carry.
Land, privacy and control differ: a house may offer private land or outdoor space and more direct control over the structure and site than a unit in a shared building. Insurance is structured differently, because a building typically carries coverage for shared elements while a unit owner insures what falls to them, and a house owner generally arranges property coverage directly. Use and leasing rules can differ, since an association's documents may restrict what a municipality would otherwise allow. And total ownership cost is assembled differently, with fees and assessments on one side and direct maintenance and repairs on the other.
The full generic comparison of these two ownership models — cost structure, responsibility and buyer profile in general terms — sits in Javier's condo versus single-family comparison. This guide stays with what the choice means for a Miami Beach buyer specifically.
Where should a buyer look in Miami Beach?
Areas within Miami Beach are best understood by what they contain rather than by ranking. The descriptions below are structural, not performance claims, and they exist to help you place your property-type decision on a map.
- South Beach, including South of Fifth: condominium-heavy, with a broad mix of building ages, sizes and architectural styles. South of Fifth is a compact, defined area south of Fifth Street with a concentrated set of buildings; the wider South Beach stock is larger and more varied.
- Mid-Beach: an oceanfront condominium corridor along Collins Avenue, together with residential streets and waterfront houses on the bay side. Two genuinely different product types sit under one area name.
- North Beach: a distinct mix, including a significant number of older and mid-century condominium buildings, residential areas and some newer projects. Building era varies widely within a short distance.
- Island and waterfront home areas: lower-density residential environments made up largely of houses, where the street and the specific site do more to define the property than the area name does.
One geography point is worth stating plainly, because the municipal distinction matters for property-specific rules and analysis: Surfside, Bal Harbour, Bay Harbor Islands and Sunny Isles Beach are separate municipalities, not parts of Miami Beach. Properties there are governed by their own local rules, and anything you read about Miami Beach does not automatically apply to them.
For how these areas actually live — the setting, the amenities and the daily-life picture — see Javier's Miami Beach community guide, which is where place and lifestyle context belongs.
What buyers should evaluate in a Miami Beach condo
A workable buyer-level framework has four parts. The first is the unit: layout and how usable the space is, floor level, exposure and outlook, condition, the quality and age of any renovation, and what parking or storage comes with it. These are the characteristics that make two units of similar size non-interchangeable.
The second is the building: its age and visible condition, the association's financial position and reserves where applicable, any assessments in place or anticipated, the insurance arrangements the building carries, the rules that govern use and alterations, the services and amenities provided, and how many comparable units are competing for buyers inside the same building right now.
The third is ownership cost, which combines the recurring fee, whatever the unit owner is responsible for directly, and any assessments where they apply. The fourth is financing: depending on the lender and the program, a condominium application can include a review of the building or project alongside the borrower, so the specific building is worth raising with your lender early.
The deeper document work — reading association financials and reserve information, understanding inspection and repair records, and structuring the diligence period — is covered in Javier's guide to buying a condo in Miami.
Why the building is part of the purchase
Comparing units without accounting for the building can hide material differences between otherwise similar residences. Buildings within a few blocks of each other can differ materially in age and condition, in the association's finances and reserve position, in assessment history, in insurance arrangements, in parking availability, in the rules that apply to owners, in the services provided, and in how much comparable inventory is competing inside them at the moment you are looking.
Each of those can affect what the unit costs to own and how it is received when it is eventually resold. That is not an argument for any particular building type or era; it is an argument for treating the building as something you evaluate on its own terms alongside the unit, using the documents and records that apply to it rather than general impressions about the area.
Floor, view, exposure, layout and condition
These are property-specific comparison factors rather than a hierarchy. A higher floor is not automatically preferable — it changes the outlook, the noise profile and sometimes the access experience, and buyers weigh those differently. A water view is a real characteristic, but so is orientation, light at different times of day, and whether the layout uses the outlook well.
Condition and renovation quality can matter as much as position. A well-configured unit in good condition and a larger unit needing work are different propositions even in the same building. It is also worth noting that an outlook depends on surrounding conditions that can change over time; a current view is not a guaranteed permanent feature of the property.
Condo fees, reserves and assessments, at a high level
What a fee covers is building-specific and document-specific. Buildings differ in what the recurring charge funds, in what services are included, and in how costs are allocated among units. For that reason, a monthly fee shown on a listing does not on its own establish what the property costs to own, and comparing fees between buildings without also comparing what they fund gives an incomplete ownership-cost picture.
Reserves and assessments belong in the same conversation. Where an association levies an assessment, it affects ownership cost beyond the regular fee, and the reserve position can affect how identified or future capital needs may be funded. of future costs. A lower fee is not automatically a sign of a weaker building, and a higher fee is not automatically a sign of a safer one — the budget, financials and records for the specific building are what answer the question. That review is set out in the condo buying guide.
What buyers should evaluate in a Miami Beach house
Start with the structure: age, condition, and the building systems where they are relevant to the property. Then the land: lot size and shape, orientation, privacy from neighbors and the street, usable outdoor space and how it relates to the house.
Renovation and permit history is worth understanding, because what was done and how it was permitted can affect both current condition and future work. Where they apply, property-specific zoning, historic-district or site constraints can shape what is possible; those are questions for the appropriate authority and your professionals on the specific property rather than a matter of general rules.
Insurance and flood circumstances are property-specific and should be quoted for the exact address. Finally, do not assume a house carries no association: some are within an HOA or subject to deed restrictions, which should be identified and read rather than presumed absent.
Waterfront homes: the extra layer
Everything that applies to a house applies to a waterfront house, plus a site-specific layer that has to be examined directly. That includes the shoreline and any seawall, and any dock or lift where one exists, along with its condition and arrangements. It includes frontage, orientation and access — how much water frontage there is, which way the site faces and how it is reached.
Where boating is part of the intended use, water depth, routes and any bridge considerations become relevant; where it is not, they matter far less. Flood and insurance circumstances are again property-specific. None of this can be inferred from an address, and it varies between neighboring properties. The technical detail sits in Javier's guide to waterfront homes in Miami.
Flood and insurance, in general terms
Insurance in Miami Beach is a property-specific question and, for a condominium, partly a building-specific one. What applies depends on the exact address, the construction and elevation of the structure, the coverage being sought and any requirements a lender imposes. For a condominium, what the building already carries affects what an individual owner needs.
The practical approach is to obtain quotes for the specific property early enough that they inform the decision, and where flood exposure is relevant, to check official flood-zone information for that address as part of due diligence rather than relying on generalizations about the area.
Total ownership cost, not purchase price
A purchase price is one number in a longer list. The checklist below is the frame worth applying to any Miami Beach property before deciding what it genuinely costs to own.
- —Purchase price, and financing costs where a loan is involved
- —Property taxes, which are property-specific and owner-specific
- —Insurance appropriate to the property and, for a condominium, the arrangements the building already carries
- —Recurring association or HOA fees where applicable
- —Assessments where an association levies them
- —Direct maintenance the owner is responsible for
- —Foreseeable repairs and replacements based on condition and age
- —Utilities and services not covered elsewhere
- —Parking or storage costs where these are separate
The distinctions by property type are straightforward. For a condominium, some recurring shared-building costs are reflected in association fees, while the owner remains responsible for unit-level costs and assessments where applicable. For a house, more maintenance and repair costs are handled directly by the owner, with HOA fees where an association applies. For a waterfront home, the site elements — shoreline structures and anything at the water's edge — add maintenance items an inland house does not have.
New construction and resale in Miami Beach
These are evaluated differently rather than ranked against each other. A resale property exists: it can be visited and inspected, the building and association where applicable have a record, and condition is observable. A new or pre-construction purchase is evaluated from plans, specifications and developer documentation, on a delivery timeline, under contract terms that differ from a resale contract.
Which suits a buyer depends on timing, tolerance for uncertainty and what is actually available in the area and property type being considered. For current projects, see Javier's new developments page; for how the purchase process itself works, see his new construction buying guide.
Use and leasing rules, where your plans depend on them
If what you intend to do with the property depends on being able to lease it, this belongs in due diligence rather than after closing. Two separate layers can apply: the municipal rules governing the property, and the governing documents of the condominium association or HOA where one exists. Both layers must be checked; if either the applicable municipal rules or the governing documents prohibit the intended use, the buyer should not assume the use is permitted.
Rules are not uniform across the city or across buildings, so what applies to one property tells you little about another. Verify the position for the exact property and building before you commit, with the relevant authority and the association's documents.
How should a buyer compare two properties?
For valuation and comparable-sales analysis, start with genuinely similar property types. A buyer can still compare a condo with a house as an ownership or lifestyle decision, but price evidence should not treat the two categories as interchangeable.
- Condo against condo: the building and its association, the unit's own characteristics, the ownership cost including fees and any assessments, condition, the units currently competing, and the recent comparable sales that apply.
- House against house: the structure, the land, the street and immediate location, condition and permit history, the houses currently competing, and the comparable sales that apply.
- Waterfront against waterfront: everything a house comparison covers, plus the site-specific waterfront layer — shoreline, dock arrangements where present, frontage, orientation and access.
One caution: price per square foot is not a universal formula for comparing a condominium against a house. The two carry different cost structures and different things are included, so a per-foot figure across categories can obscure differences in land, association obligations, maintenance responsibility and other property-specific characteristics.
What to review before making an offer
Before an offer, and certainly before removing contingencies, a buyer should be able to answer most of the following about the specific property.
- What type of ownership is this, and what exactly comes with it?
- What does the genuinely competing set of properties look like right now?
- Which comparable properties closed recently, and on what terms?
- What is the condition of the property, and what work is foreseeable?
- For a condominium: what do the building, association finances, fees, any assessments and the rules show?
- For a house: what do the lot, structure, permit history and any HOA or deed restrictions show?
- For a waterfront property: what is the condition of the site, seawall, dock and access where these are relevant?
- Have you obtained insurance quotes and, where relevant, flood information for this address?
- Has your lender confirmed the financing path, including any building or project review?
- Has your intended use been verified against municipal rules and the governing documents?
- What is the total ownership cost, not just the price?
- What remains genuinely uncertain, and what contract review period or contingency, if any, applies to that issue?
Working through that list on a specific property, and negotiating from what it shows, is what buyer representation is for. The wider purchase process from search through closing is set out in Javier's guide to buying property in Miami.
Current market conditions versus this guide
This guide is about evaluating property choices, and it deliberately avoids current figures, which would be stale quickly and would not describe a specific property in any case. For how the Miami Beach market is structured and interpreted locally, see Javier's Miami Beach market overview. For live inventory, use the Miami property search.
A sensible next step
- To see what is currently available, use the Miami property search.
- To have a specific property evaluated and negotiated, see Javier's buyer representation.
- For location and lifestyle orientation, read the Miami Beach community guide.
- For local market context, read the Miami Beach market overview.
- For deeper condominium due diligence, read how to buy a condo in Miami.